The 50/30/20 Budget Rule: Does It Actually Work in the UK?
The 50/30/20 Budget Rule: Does It Actually Work in the UK?
The 50/30/20 rule is the most quoted budgeting advice on the internet: spend 50% of your take-home pay on needs, 30% on wants, and save 20%. Simple, memorable, and — if you live in London — completely detached from reality. I tried following it strictly when I first moved here and spent three months feeling like a financial failure before realising the rule was wrong, not me. Here’s an honest assessment of where it works, where it breaks, and what to do instead.
How the 50/30/20 Budget Rule Works
Popularised by US Senator Elizabeth Warren in her book All Your Worth, the rule divides your after-tax income into three buckets:
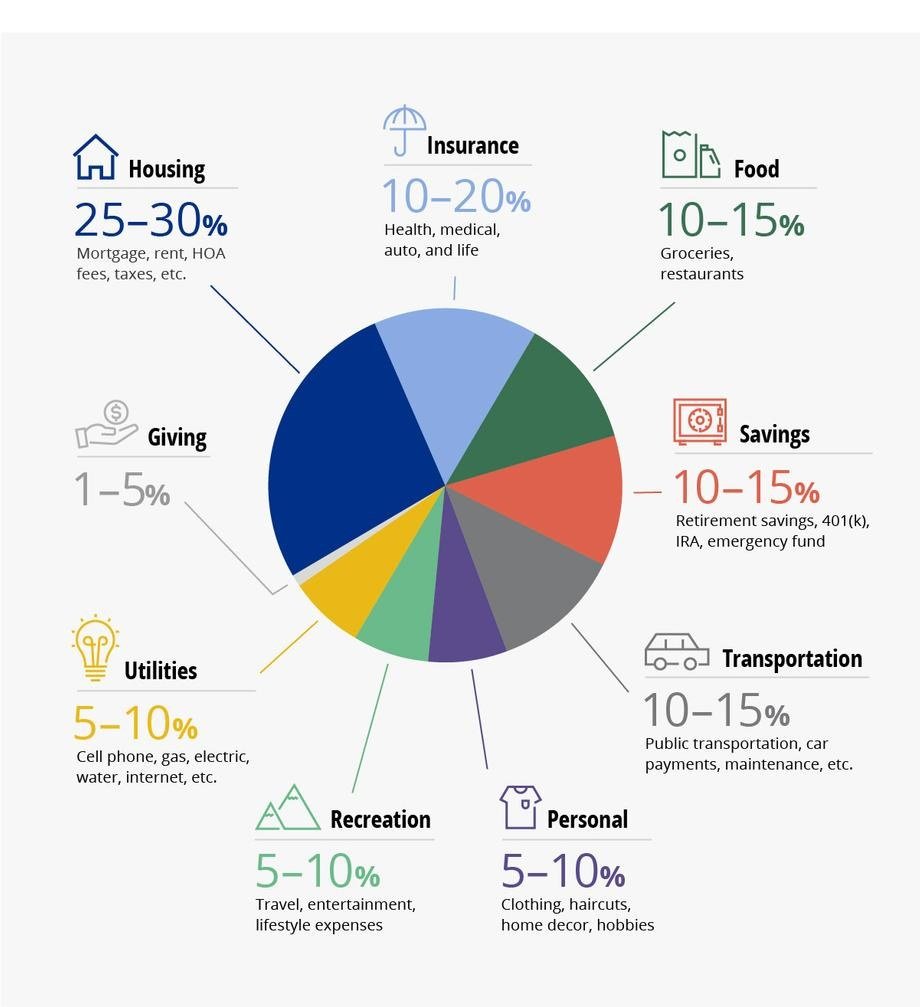
- 50% — Needs: rent or mortgage, bills, groceries, transport, insurance, minimum debt payments. The non-negotiables.
- 30% — Wants: eating out, holidays, hobbies, subscriptions, clothes you don’t strictly need. The fun stuff.
- 20% — Savings and debt repayment: emergency fund, pension top-ups, ISA contributions, overpaying debt beyond minimums.
The appeal is obvious: no spreadsheets, no tracking every coffee, just three big buckets. And as a starting framework, it’s genuinely useful — most people have no idea what proportion of their income goes where, and this forces the question.
Where It Breaks Down in the UK
The rule was designed for American suburbs, not British cities. The problems:
- Housing costs. In London, rent alone can be 45–55% of take-home pay on an average salary. Add bills and you’re at 60%+ on “needs” before buying food. The 50% cap is fantasy for millions of renters — see our London cost of living breakdown for the real numbers.
- “Needs” vs “wants” is blurry. Is a £40/month gym membership a need (health) or a want? Is the car you need for a rural commute a need? The categories invite endless self-justifying reclassification.
- It ignores debt emergencies. If you’re paying 25% APR on £5,000 of credit card debt, “saving 20%” while minimum-paying the debt is mathematically backwards.
- One income, many realities. The rule treats a £22k earner and a £80k earner identically. Lower earners spend a far higher share on needs through no fault of their own.
A Better UK Adaptation
Don’t bin the rule — bend it. Here’s how I’d reshape it for British reality:
- Calculate your real “needs” floor. Add up rent, bills, food, transport. Whatever percentage that is — 55%, 65% — that’s your starting truth, not a failure.
- Automate savings first, even if it’s 5%. The 20% is aspirational; the automation is essential. Pay yourself on payday — see realistic monthly savings targets.
- Split the remainder between wants and extra savings. If needs are 60% and you save 10%, wants get 30%. The ratios flex; the habit doesn’t.
- Revisit when circumstances change. New job, new flat, paid-off debt — recalculate. A budget is a living thing.
Alternatives Worth Knowing
- Pay-yourself-first budgeting: Decide the savings amount, automate it, spend the rest freely. My personal favourite — it removes guilt from spending because the saving already happened.
- Zero-based budgeting: Every pound gets a job each month. Powerful but high-maintenance; great for debt payoff sprints.
- The 60% solution: 60% of gross income covers all committed expenses, then 10% each to retirement, long-term savings, short-term savings and fun money. More granular, popular with higher earners.
- No-budget budgeting: Automate bills and savings, spend the rest. Works surprisingly well for disciplined earners who hate tracking.
Whichever you pick, pair it with the foundations: an emergency fund first, then systematic saving.
My Honest Take
In my experience, 50/30/20 works well as a diagnostic (“where am I vs the ideal?”) and poorly as a prescription (“hit these numbers or else”). Use it to spot problems — if your “wants” are 45%, that’s a useful signal — but don’t beat yourself up when London rent makes 50% needs impossible. The people who build wealth aren’t the ones with the perfect ratios; they’re the ones who automated £200 a month five years ago and never thought about it again.
50/30/20 in Practice: A Worked London Example
Let’s run the numbers for a realistic London scenario — £38,000 salary, ~£2,450/month take-home, renting a room at £950:
- Needs (50% = £1,225): rent £950 + bills £120 + transport £160 + basic groceries £200 = £1,430. Already 58% — the rule breaks immediately, exactly as predicted.
- Adapted reality: needs 58% (£1,430), savings 12% (£295 automated on payday), wants 30% (£725). Total: 100%.
- The insight: this person saves nearly £3,500/year — a genuinely good outcome — while “failing” the 50/30/20 rule. The rule’s percentages were wrong; the behaviour (automated saving, conscious spending) is right.
This is why I tell people to use the rule as a mirror, not a cage. Calculate your actual splits, compare loosely to 50/30/20, and ask: “is my savings rate where I want it, and is my wants spending intentional?” If yes, the percentages don’t matter. If no, you now know which bucket to squeeze — usually wants, sometimes (painfully) needs via the big levers: housing, transport, food. Our London cost breakdown and weekly shop guide show where the money goes.
Common 50/30/20 Mistakes
- Counting debt minimums as “savings”. Minimum payments are needs (obligations); only overpayments count toward the 20%.
- Ignoring irregular expenses. Christmas, car MOTs, annual insurance — divide by 12 and put them in needs monthly, or they ambush the budget. These are “sinking funds”, and budgeting without them is fantasy.
- Classifying wants as needs. The £60/month gym you visit twice is a want. So is the Deliveroo habit. Honesty here is the whole game.
- Setting it and forgetting it for years. Recalculate annually or when income/housing changes. A budget from 2023 is a historical document.
- Aiming for perfection immediately. Start with tracking for a month (no judgment), then set targets. You can’t optimise what you haven’t measured.
For the full savings system beyond budgeting frameworks, the MoneySavingExpert budget planner is the best free tool in the UK — an hour with it beats a month of guessing. And our emergency fund guide remains step one of any plan, whatever framework you choose.
The Practical Takeaway
50/30/20 is a decent starting framework but a bad strict rule for most UK renters — housing costs alone break it. Adapt it: know your true needs percentage, automate whatever you can save (even 5%), and spend the rest without guilt. Review it yearly, not daily. And if you want the numbers that make any budget work in the capital, our guide to making friends in London proves the best things here are free anyway.